Global Automotive E/E Architecture Market 2024–2033
Automotive E/E Architecture Market Size, Trends and Insights By Vehicle Type (Passenger Vehicle, Commercial Vehicle), By Propulsion (IC-Engine, Electric), By Component (Hardware, Software), and By Region - Global Industry Overview, Statistical Data, Competitive Analysis, Share, Outlook, and Forecast 2024–2033
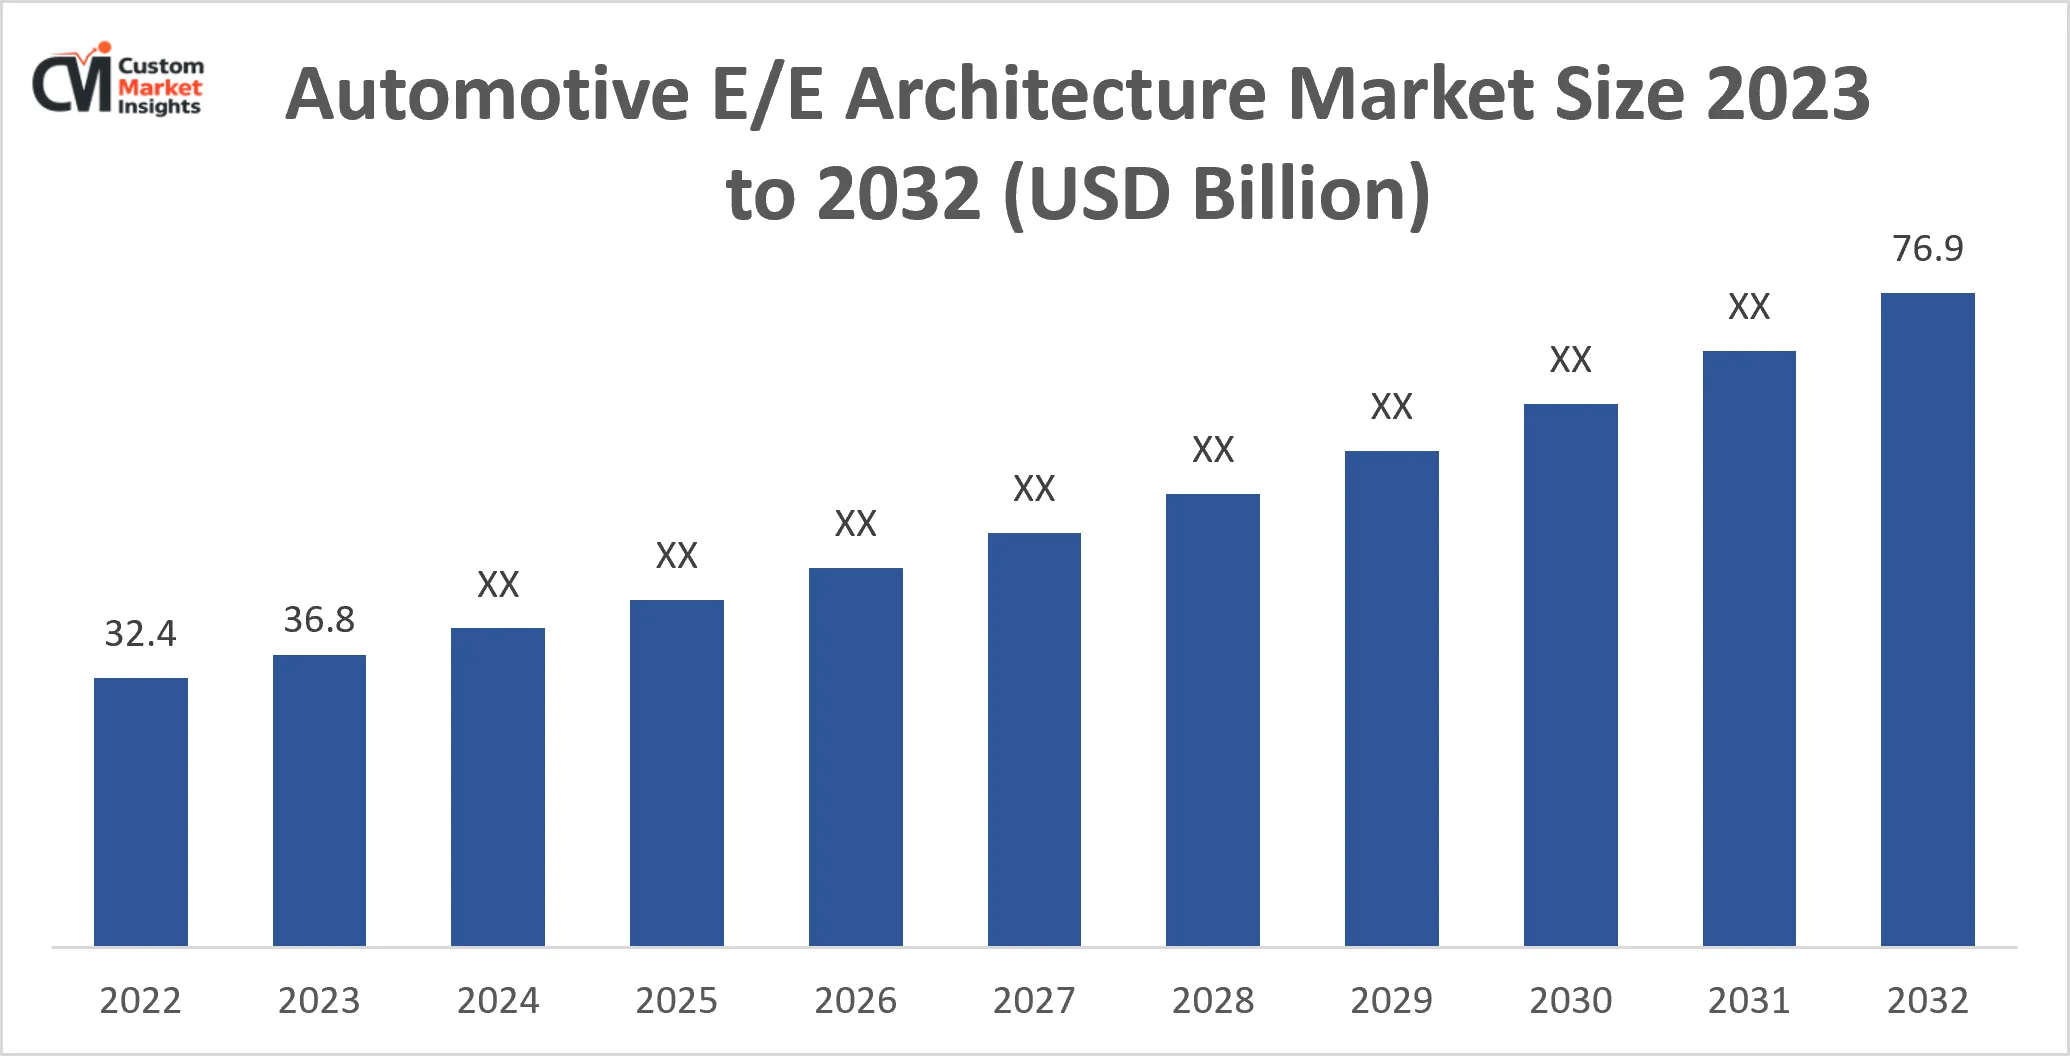
The global automotive e/e architecture market was valued at USD 36.8 Bn in 2023 and is projected to reach USD 76.9 Bn by 2032, growing at a CAGR of 8.4%. Europe is the largest regional market and Asia-Pacific is growing fastest.
Global Automotive E/E Architecture Market 2023–2032 (By Billion)
As per the current market research conducted by CMI Team, the global Automotive E/E Architecture Market is expected to record a CAGR of 8.4% from 2023 to 2032. In 2022, the market size is projected to reach a valuation of USD 32.4 billion. By 2032, the valuation is anticipated to reach USD 76.9 billion.
Electric car sales, 2020-2023* (Millions)
2020
2021
2022
2023*
China
1.1
3.3
6.0
8.0
Europe
1.4
2.3
2.7
3.4
US
0.3
0.6
1.0
1.6
Others
0.2
0.3
0.6
0.9
Source: According to IEA Org.
The Automotive E/E Architecture Market refers to the industry segment that deals with the design, development, and integration of electrical and electronic systems within vehicles. Automotive E/E architectures enable the smooth operation of vehicle elements like powertrain, infotainment, connectivity, ADAS, and autonomous driving.
The market is marked by swift technological progress, changing customer preferences, and a drive for innovation. It involves collaboration among automakers, suppliers, and technology providers to deliver sophisticated and reliable E/E architectures.
Key trends include increasing vehicle electrification, growing demand for connectivity and ADAS features, a software-centric approach with over-the-air updates, safety and redundancy requirements, emphasis on lightweight and modular solutions, and recovery efforts from the COVID-19 pandemic.
The Automotive E/E Architecture Market presents significant growth opportunities due to several factors:
Vehicle Electrification: The increasing demand for electric and hybrid vehicles is driving the need for advanced E/E architectures that can support the complex powertrain systems and battery management required for efficient and sustainable electric mobility.
Connectivity and ADAS Features: The growing popularity of connected vehicles and Advanced Driver Assistance Systems (ADAS) is fuelling the demand for sophisticated E/E architectures that can seamlessly integrate sensors, communication modules, and other components to enable advanced safety and infotainment features.
Autonomous Driving Technology: The development of autonomous driving technology requires highly advanced and reliable E/E architectures to manage a wide array of sensors, AI algorithms, and communication networks, enabling vehicles to operate safely and autonomously.
Software-Centric Solutions: With the increasing importance of software-driven functionalities in vehicles, there are opportunities for E/E architecture providers to develop flexible and scalable solutions that facilitate easy integration of software updates, enhance vehicle diagnostics, and support over-the-air updates.
Lightweight and Modular Architectures: As the automotive industry emphasizes fuel efficiency and sustainability, opportunities exist for developing lightweight and modular E/E architectures that can optimize space utilization, reduce vehicle weight, and enhance overall energy efficiency.
Safety and Redundancy Solutions: There is a growing need for E/E architectures with built-in safety features and redundancy mechanisms to ensure reliable and fail-safe operation, particularly in autonomous vehicles. Providers can seize opportunities by offering solutions that comply with stringent safety standards and address customer concerns about vehicle reliability and security.
Automotive E/E Architecture Market - Mergers and Acquisitions
The Automotive E/E Architecture Market has seen several mergers and acquisitions in recent years, with companies seeking to expand their market presence and leverage synergies to improve their product offerings and profitability. Some notable examples of mergers and acquisitions in the Automotive E/E Architecture Market include:
Aptiv PLC and Hyundai Motor Group: In 2019, Aptiv and Hyundai formed a joint venture to develop and commercialize autonomous driving technology. The partnership aimed to leverage Aptiv's expertise in E/E architectures and Hyundai's manufacturing capabilities to accelerate the deployment of autonomous vehicles.
NVIDIA Corporation and Mercedes-Benz: In 2020, NVIDIA announced a partnership with Mercedes-Benz to develop a software-defined vehicle architecture for the entire Mercedes-Benz fleet. The collaboration focused on creating a unified, flexible platform capable of supporting AI-driven features and future upgrades.
Samsung Electronics Acquires Harman International Industries, Inc.: In 2017, Samsung acquired Harman International, a major player in automotive infotainment and connectivity solutions. This acquisition expanded Samsung's presence in the automotive sector, enabling the integration of Harman's E/E architectures with Samsung's technologies.
Aptiv PLC Acquires Kodiak Robotics: In January 2019, Aptiv acquired Kodiak Robotics, a startup focused on developing autonomous trucking technology. This acquisition furthered Aptiv's capabilities in autonomous driving and E/E architectures, with a specific focus on commercial vehicles and logistics solutions.
Hyundai Motor Group Acquires Boston Dynamics: In June 2020, Hyundai Motor Group acquired a controlling stake in Boston Dynamics, a renowned robotics company known for its advanced mobility solutions. This acquisition allowed Hyundai to tap into Boston Dynamics' expertise in robotics and mobility technologies, potentially enhancing Hyundai's capabilities in developing futuristic E/E architectures for autonomous vehicles and robotics applications. The partnership opened up new opportunities for innovation and integration of cutting-edge technologies in the automotive industry.
These mergers and acquisitions helped companies expand their product offerings, improve their market presence, and capitalize on growth opportunities in the Automotive E/E Architecture Market. The trend is expected to continue as companies seek to gain a competitive edge in the market.
The Automotive E/E Architecture Market faces several significant threats that could impact its growth and profitability in the future. Some of these threats include:
Cybersecurity Risks: As vehicles become more connected and reliant on electronic systems, the threat of cyberattacks increases. Malicious actors could target E/E architectures, compromising critical functions, and potentially causing accidents or theft of sensitive data, leading to safety and privacy concerns for consumers.
Complexity and Reliability Challenges: The increasing complexity of E/E architectures, with numerous interconnected components and software modules, poses challenges in ensuring their reliability and robustness. Failures or malfunctions in these intricate systems can lead to costly recalls, reputational damage, and decreased customer trust in automotive brands.
Rapid Technological Obsolescence: The automotive industry experiences rapid technological advancements, and E/E architectures can quickly become outdated. Manufacturers face the risk of investing in technologies that might become obsolete before they can recoup their investments, leading to financial losses and inefficiencies.
Supply Chain Disruptions: The automotive E/E architecture market heavily relies on a global supply chain for components and materials. Disruptions such as natural disasters, trade disputes, or geopolitical tensions can lead to shortages and delays in production, affecting vehicle manufacturing and sales, and potentially leading to higher costs for manufacturers.
Report Scope
Feature of the Report
Details
Market Size in 2023
USD 36.8 Billion
Projected Market Size in 2032
USD 76.9 Billion
Market Size in 2022
USD 32.4 Billion
CAGR Growth Rate
8.4% CAGR
Base Year
2023
Forecast Period
2024-2033
Key Segment
By Vehicle Type, Propulsion, Component and Region
Report Coverage
Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends
Regional Scope
North America, Europe, Asia Pacific, Middle East & Africa, and South & Central America
Buying Options
Request tailored purchasing options to fulfil your requirements for research.
Category-Wise Insights
By Vehicle Type:
Passenger Vehicle: The Automotive E/E Architecture Market for passenger vehicles involves designing and integrating electrical and electronic systems for cars, SUVs, and other personal-use vehicles. Trends include increasing demand for connected infotainment, advanced driver assistance systems (ADAS), and electric powertrains to meet consumer preferences for safety, convenience, and sustainability.
Commercial Vehicle: The Automotive E/E Architecture Market for commercial vehicles focuses on electrical and electronic systems integration for trucks, buses, and vans used for transportation and logistics. Trends include the adoption of advanced driver assistance technologies, fleet management solutions, and electrification to improve efficiency, safety, and environmental performance in the commercial vehicle sector.
By Propulsion
IC-Engine: IC-Engine stands for Internal Combustion Engine. In the Automotive E/E Architecture Market, IC-Engine systems involve complex electronic control units to optimize engine performance, fuel efficiency, and emissions. The trend in this segment includes integrating advanced sensors and actuators for precise engine control, complying with stringent emission norms, and implementing engine start-stop systems for improved fuel economy.
Electric: Electric systems pertain to the growing domain of electric and hybrid vehicles. In the Automotive E/E Architecture Market, electric architectures incorporate sophisticated power electronics, battery management systems, and motor control units. The trend here includes advancements in battery technology, fast-charging infrastructure integration, and innovative energy recuperation strategies for enhanced electric vehicle range and performance.
By Component
Hardware: The physical components used to build the electrical and electronic systems within vehicles. This includes sensors, microcontrollers, ECUs, wiring harnesses, and other electronic elements responsible for data processing and communication. The current trends in hardware include a focus on miniaturization to optimize space, integration of advanced sensors to support ADAS and autonomous driving features, and the use of high-performance microcontrollers to handle the increasing complexity of modern vehicle functionalities.
Software: The programs and code that control the behaviour of electronic components within the vehicle's electrical systems. It includes operating systems, firmware, algorithms, and application software responsible for seamless communication, data processing, and activation of various features. Current trends in E/E architecture software involve a shift towards software-defined architectures, allowing for over-the-air updates and remote software upgrades. There is also a growing adoption of AI and machine learning algorithms to enable advanced functionalities like predictive maintenance and personalized driver assistance. Cybersecurity measures are gaining importance to safeguard software and data from potential cyber threats, given the growing connectivity of vehicles.
The Automotive E/E Architecture Market is segmented into various regions, including North America, Europe, Asia-Pacific, and LAMEA. Here is a brief overview of each region:
North America: In North America, trends in the Automotive E/E Architecture Market include a strong focus on connected and autonomous vehicles, with major automakers and tech companies investing in advanced E/E architectures to support these technologies. The region is also witnessing increasing demand for electric vehicles, driving the need for E/E architectures optimized for electric powertrains and battery management. Some of the dominating market players in North America include Aptiv PLC, General Motors, Tesla, Inc., and Ford Motor Company. Aptiv is a leading supplier of advanced E/E architectures and autonomous driving solutions, while Tesla has been at the forefront of electric vehicle technology, driving innovations in E/E architectures for EVs.
Europe: In Europe, key trends in the Automotive E/E Architecture Market revolve around sustainability and regulatory compliance. With stringent emissions regulations, the region emphasizes electrification and lightweight materials, influencing the design of E/E architectures for improved energy efficiency. Europe also leads in integrating advanced ADAS features into vehicles, requiring robust E/E architectures to support these functionalities. Dominating the European market are companies like Continental AG, Robert Bosch GmbH, and Volkswagen Group. Continental AG and Bosch are renowned for their comprehensive E/E architecture solutions, while Volkswagen Group's brands focus on innovative E/E architectures to enhance vehicle performance and sustainability.
Asia-Pacific: In the Asia-Pacific region, automotive E/E architecture trends are driven by the rapid adoption of electric vehicles, particularly in countries like China. There is a strong emphasis on cost-effective and scalable solutions to meet the growing demand for EVs. Asia-Pacific also leads in the development of smart and connected car technologies, fostering advancements in E/E architectures to support seamless integration. Leading market players in Asia-Pacific include Toyota Motor Corporation, Hyundai Motor Group, and BYD Company Limited. Toyota is a major player in the region, investing in innovative E/E architectures to enhance vehicle safety and efficiency. Hyundai is known for its advancements in E/E architectures for autonomous vehicles, while BYD is a significant player in the electric vehicle market, driving innovations in EV-specific E/E architectures.
LAMEA (Latin America, Middle East, and Africa): LAMEA is witnessing a growing interest in connected technologies and ADAS features, driving demand for E/E architectures that can support these functionalities. The region also shows potential for electric vehicle adoption, with several countries focusing on sustainable mobility solutions, influencing the development of relevant E/E architectures. While the E/E Architecture Market in LAMEA is relatively nascent, some key players are making strides in the region. Examples include NIO Inc., an emerging Chinese electric vehicle manufacturer, which is expanding its presence in the Middle East and Africa, and Valeo S.A., a leading automotive supplier known for its innovative E/E architecture solutions.
The Automotive E/E Architecture Market is highly competitive, with a large number of manufacturers and retailers operating globally. Some of the key players in the market include:
Robert Bosch GmbH
Continental AG
Aptiv PLC
ZF Friedrichshafen AG
DENSO Corporation
Panasonic Corporation
Lear Corporation
Veoneer Inc.
Magna International Inc.
Harman International Industries Inc.
Others
These companies operate in the market through various strategies such as product innovation, mergers and acquisitions, and partnerships. For example, in 2021, a major partnership in the Automotive E/E Architecture Market was formed between BMW Group and NVIDIA Corporation. The collaboration aimed to develop a next-generation E/E architecture to power the BMW fleet, leveraging NVIDIA's advanced AI computing technology for enhanced autonomous driving capabilities and smart connectivity features.
New players entering the Automotive E/E Architecture Market are adopting innovation and development to establish their presence. Startups and tech companies are focusing on software-defined architectures, AI-based solutions, and modular designs to offer cost-effective and scalable E/E systems. These newcomers often aim to disrupt traditional market dynamics with agile and cutting-edge technologies.
In contrast, key players dominating the market are established, automotive suppliers and technology giants. These companies have extensive expertise, a wide customer base, and strong R&D capabilities, allowing them to offer comprehensive E/E architecture solutions for various vehicle types. Dominating players invest heavily in research, collaborate with automakers, and lead in developing advanced ADAS, autonomous driving, and connectivity features, solidifying their market position.
Regional Coverage
North America
U.S.
Canada
Mexico
Rest of North America
Europe
Germany
France
U.K.
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
New Zealand
Australia
South Korea
Rest of Asia Pacific
The Middle East & Africa
Saudi Arabia
UAE
Egypt
Kuwait
South Africa
Rest of the Middle East & Africa
Latin America
Brazil
Argentina
Rest of Latin America
CMI.Market Research Report2023-2032
Get the full report
Updated: September 2026 · Formats: PDF, Excel, PPT
Which are the driving factors of the Automotive E/E Architecture Market?
The key factors driving the Market are Vehicle Electrification, Connectivity and ADAS Features, Autonomous Driving Technology, Software-Centric Solutions, Lightweight and Modular Architectures And Safety and Redundancy Solutions.
Which type led the Automotive E/E Architecture market?
The "Vehicle Type" category dominated the market in 2022.
Who are the key players in the Automotive E/E Architecture market?
The key players in the market are Robert Bosch GmbH, Continental AG, Aptiv PLC, ZF Friedrichshafen AG, DENSO Corporation, Panasonic Corporation, Lear Corporation, Veoneer Inc., Magna International Inc., Harman International Industries Inc., Others.
Which region held the largest market share in the Automotive E/E Architecture market?
"North America" had the largest share in the Automotive E/E Architecture Market.
What is the growth rate of the Automotive E/E Architecture market?
The global market is projected to grow at a CAGR of 8.4% during the forecast period, 2023-2032.
How much is the Automotive E/E Architecture market?
The Automotive E/E Architecture Market size was valued at USD 32.4 Billion in 2022.
Ayush Kadam is a Senior Market Research Analyst at Custom Market Insights, with over seven years of experience in syndicated and custom market research. He specializes in market sizing, competitive intelligence, industry trends, forecasting, and strategic insights, helping clients turn complex data into actionable business decisions.