Market size, share and growth analysis by nature, source, product type and pet type, with forecasts for 2023–2032. The competitive landscape profiles 10+ companies.
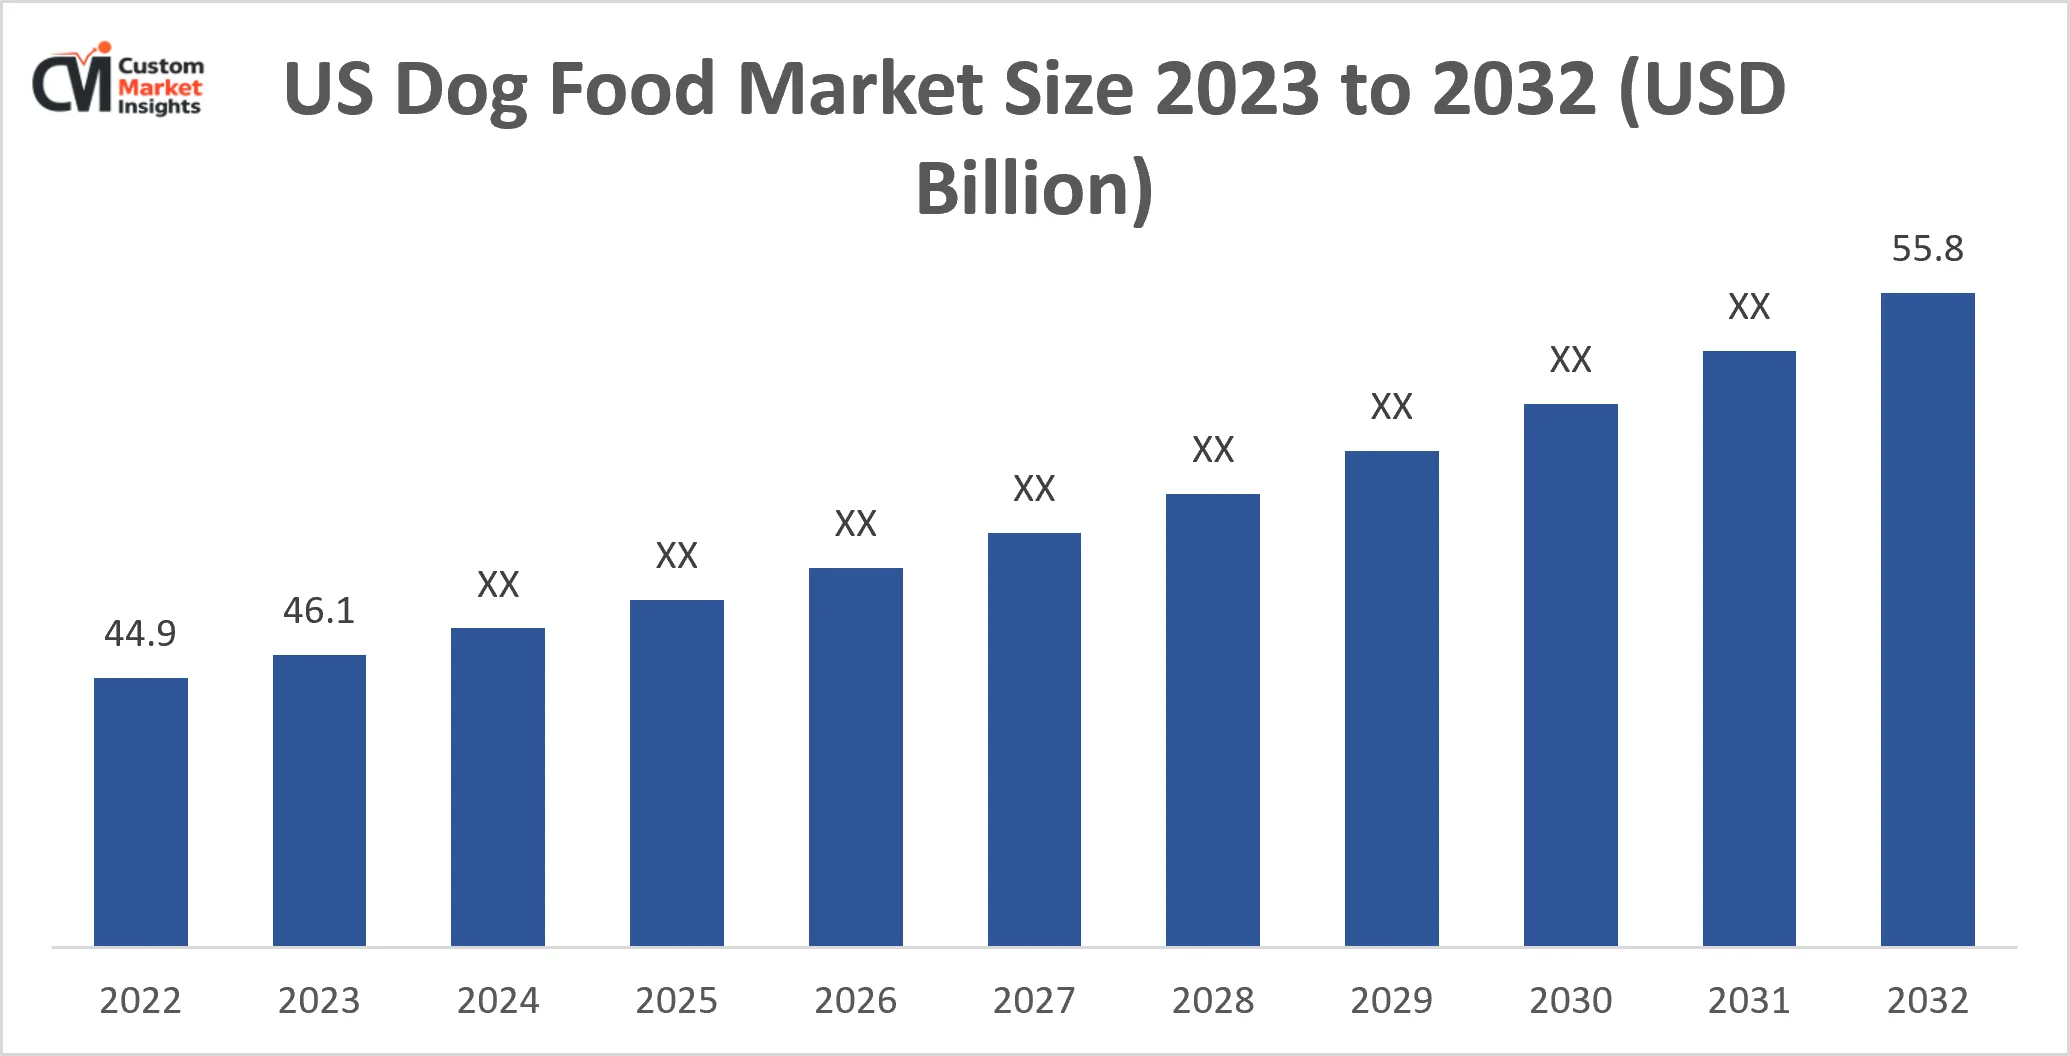
The US dog food market was valued at USD 46.1 Bn in 2023 and is projected to reach USD 55.8 Bn by 2032, growing at a CAGR of 4.6%. USA is both the largest and the fastest-growing regional market.
Reports Description
As per the current market research conducted by CMI Team, the US Dog Food Market is expected to record a CAGR of 4.6 % from 2023 to 2032. In 2022, the market size is projected to reach a valuation of USD 44.9 billion. By 2032, the valuation is anticipated to reach USD 55.8 billion.
The dog food market refers to the industry that produces and sells food specifically designed for dogs. It encompasses a wide range of products, including dry kibble, wet/canned food, semi-moist food, freeze-dried or dehydrated food, and specialty diets tailored to specific nutritional needs or dietary preferences of dogs.
The dog food market serves as a crucial segment of the larger pet food industry, catering to dogs' dietary requirements and preferences to ensure their overall health, well-being, and nutritional balance. It includes various brands, manufacturers, distributors, and retailers that offer a diverse range of dog food options to meet the demand of pet owners. The market is influenced by factors such as pet ownership trends, consumer preferences, nutritional research, and regulatory standards.
The US Dog Food Market offers significant growth prospects due to several key factors:
Increasing Pet Ownership: The number of pet owners in the US is on the rise, driven by factors such as companionship, emotional support, and the trend of nuclear families. This growing pet ownership contributes to a higher demand for dog food products.
Humanization of Pets: Pets are increasingly seen as part of the family, and pet owners are willing to spend more on high-quality, nutritious food for their dogs. The trend of humanization of pets has led to a shift towards premium and specialized dog food products, creating opportunities for market growth.
Health and Wellness Focus: There is a growing awareness among pet owners about the importance of proper nutrition and the impact it has on the health and well-being of their dogs. This has resulted in a rising demand for dog food that offers specific health benefits, such as weight management, joint health, and digestive health.
Premiumization and Innovation: The market is witnessing a trend of premiumization, where pet owners are willing to pay more for high-quality and innovative dog food products. Manufacturers are introducing new and unique formulations, including natural and organic options, grain-free diets, and novel protein sources, to cater to the evolving preferences of pet owners.
E-commerce and Direct-to-Consumer Channels: The growth of e-commerce platforms and direct-to-consumer channels has provided convenience and accessibility to pet owners, allowing them to easily purchase dog food products online. This has expanded the reach of manufacturers and increased market penetration.
Focus on Sustainability and Ethical Sourcing: There is a rising emphasis on sustainability and ethical sourcing in the pet food industry. Consumers are increasingly seeking environmentally friendly and ethically sourced ingredients in dog food products, presenting opportunities for market players who prioritize sustainability practices.
Veterinary Recommendations and Prescription Diets: Veterinary recommendations and prescription diets play a significant role in the dog food market. As veterinarians emphasize the importance of proper nutrition for dogs with specific health conditions, a growing demand for specialized prescription diets drives the market growth in this segment.
Overall, these factors contribute to the positive growth prospects in the US Dog Food Market, making it an attractive industry for existing and new players to innovate, expand their product offerings, and meet the evolving needs of pet owners.
US Dog Food Market - Mergers and Acquisitions
The US Dog Food Market has witnessed various mergers and acquisitions, which have had a significant impact on the industry landscape. While I can provide information on some notable mergers and acquisitions in the past, please note that my knowledge is based on information available until September 2021, and there may have been more recent developments. Here are a few examples:
Mars Incorporated: Mars is a major player in the pet food industry and has made several acquisitions to strengthen its position in the US dog food market. In 2014, Mars acquired Procter & Gamble's pet food brands, including Iams, Eukanuba, and Natura. This acquisition expanded Mars' portfolio and market share in the US.
The J.M. Smucker Company: In 2015, J.M. Smucker acquired Big Heart Pet Brands, which included well-known dog food brands such as Milk-Bone and Kibbles 'n Bits. This acquisition helped J.M. Smucker enter the pet food market and diversify its product offerings.
Nestlé Purina PetCare: Nestlé Purina PetCare, a division of Nestlé, has also been active in the mergers and acquisitions space. In 2013, Nestlé Purina acquired Merrick Pet Care, a natural and organic pet food company, which helped expand its presence in the high-quality and premium dog food segment.
General Mills: In 2018, General Mills acquired Blue Buffalo Pet Products, a leading natural pet food company known for its Blue Buffalo brand. This acquisition allowed General Mills to enter the fast-growing natural pet food segment and strengthen its position in the dog food market.
The J.M. Smucker Company (Continued): In 2020, J.M. Smucker acquired Ainsworth Pet Nutrition, the maker of Rachael Ray Nutrish dog food. This acquisition further expanded J.M. Smucker's portfolio and presence in the premium dog food segment.
COMPARATIVE ANALYSIS OF THE RELATED MARKET
US Dog Food Market
US Animal Healthcare Market
Pet Supplement Market
CAGR 4.6% (Approx)
CAGR 10.3%
(Approx)
CAGR 6%
(Approx)
USD 55.8 Billion by 2032
USD 11.3 Billion by 2030
USD 3.1 Billion by 2032
US Dog Food Market - Significant Threats
While the US Dog Food Market offers significant growth prospects, there are also potential threats that could impact the industry. Here are some significant threats to consider:
Competition from New Entrants: The dog food market is highly competitive, and the entry of new players with innovative products and marketing strategies can pose a threat to established brands. New entrants may disrupt market dynamics and attract consumers with unique offerings, challenging the market share of existing companies.
Shifting Consumer Preferences: Consumer preferences and trends can change over time, and shifts in demand for certain types of dog food or dietary preferences can pose challenges for manufacturers. For example, if there is a sudden shift towards alternative diets like raw or homemade food, it may impact the demand for commercial dog food.
Regulatory Changes: Changes in regulations related to pet food manufacturing, labeling, or ingredient sourcing can pose challenges for companies in the dog food market. Compliance with new regulations may require adjustments to formulations, production processes, or packaging, which could affect costs and market competitiveness.
Economic Factors: Economic conditions, such as recessions or fluctuations in disposable income, can impact consumer spending on pet products, including dog food. During periods of economic uncertainty, consumers may opt for lower-priced options or reduce discretionary spending, which could affect sales and profitability for dog food companies.
Supply Chain Disruptions: Disruptions in the supply chain, including raw material shortages, transportation issues, or natural disasters, can impact the availability and cost of ingredients used in dog food production. Such disruptions can lead to increased costs or production delays, affecting the market and potentially leading to price fluctuations.
Negative Public Perception or Recalls: Any negative incidents, such as product recalls or concerns about the safety and quality of dog food, can damage consumer trust and impact the reputation of brands and the entire industry. Maintaining strict quality control measures and transparent communication is crucial to mitigating this threat.
Health and Safety Concerns: The emergence of health issues, food safety concerns, or the perception of ingredients with potential health risks can influence consumer behaviour and preferences. Increased awareness of specific health conditions or allergies may lead pet owners to seek specialized diets or alternative feeding options, impacting the demand for traditional dog food.
Report Scope
Feature of the Report
Details
Market Size in 2023
USD 46.1 Billion
Projected Market Size in 2032
USD 55.8 Billion
Market Size in 2022
USD 44.9 Billion
CAGR Growth Rate
4.6% CAGR
Base Year
2023
Forecast Period
2024-2033
Key Segment
By Nature, Source, Product Type, Pet Type, Packaging Type, Distribution Channel, and Region
Report Coverage
Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends
Regional Scope
North America, Europe, Asia Pacific, Middle East & Africa, and South & Central America
Buying Options
Request tailored purchasing options to fulfil your requirements for research.
Category-Wise Insights
Organic Segment:
The demand for organic dog food is experiencing significant growth due to several factors. Firstly, consumers are increasingly concerned about the ingredients used in their pets' food. They want to ensure that their furry companions receive the same quality and health benefits that they seek from their own food. This trend aligns with the rising popularity of organic food in human consumption.
Pet owners are looking for dog food options that are free from artificial colors, preservatives, pesticides, and flavors. They also prefer products that do not contain synthetic hormones or antibiotics. By opting for organic dog food, pet owners believe they are providing their dogs with healthier and more natural nutrition.
To cater to this growing market trend, dog food manufacturers are launching new brands and expanding their offerings to include a diverse range of organic dog food options. By capitalizing on the demand for organic pet food, these manufacturers aim to attract health-conscious consumers and meet their expectations for high-quality, natural ingredients. As a result, the demand for organic dog food is projected to continue growing, with a compound annual growth rate (CAGR) of 7.9%. This trend reflects the evolving preferences of pet owners who prioritize the health and well-being of their dogs and seek organic alternatives to conventional dog food products.
Pet Type:
The adult dog category is projected to hold a significant share of the dog food market, estimated to account for 58.6% and reach a valuation of US$ 26.26 billion by 2031. The segment is expected to witness healthy growth throughout the forecast period. This dominance of the adult dog category can be attributed to several factors, including the active nature of adult dogs and their high appetite.
One of the key reasons behind the adult dog category's prominence is the active nature of adult dogs, which leads to higher energy expenditure and, consequently, increased food consumption. Adult dogs require sufficient nutrition to support their energy levels and overall health, driving the demand for dog food within this segment.
Additionally, adult dogs tend to have established dietary preferences and nutritional requirements, making them a reliable and consistent consumer base for dog food manufacturers. Their stable dietary needs contribute to the sustained demand within the adult dog category. Considering these factors, it is expected that the demand for dog food in the adult dog segment will continue to grow steadily, supporting the overall growth of the dog food market. Manufacturers and brands catering to the nutritional needs of adult dogs are likely to capitalize on this market opportunity by offering a diverse range of products specifically tailored for adult dogs.
US Dog Food Market - Regional Analysis
Regional analysis of the US Dog Food Market reveals variations in consumer preferences and market dynamics across different regions of the country. While I can provide a general overview, please note that specific data and trends may vary over time and depending on the sources. Here is a broad regional analysis of the US dog food market:
Northeast Region: The Northeast region, including states such as New York, Pennsylvania, and Massachusetts, has a sizable pet population and a strong demand for premium dog food products. Pet owners in this region often prioritize high-quality ingredients, natural and organic options, and specialty diets. There is also a growing interest in alternative and grain-free dog food varieties.
Southeast Region: The Southeast region, comprising states such as Florida, Georgia, and North Carolina, has a large pet population and a diverse consumer base. The region is characterized by a mix of urban and rural areas, with varying preferences for dog food. While there is demand for mainstream dog food brands, there is also an increasing interest in natural, grain-free, and specialized diets catering to specific health needs.
Midwest Region: The Midwest region, including states such as Illinois, Ohio, and Michigan, has a significant pet ownership rate and a diverse market landscape. Consumers in this region tend to prioritize affordability and value for money while seeking reliable and trusted dog food brands. There is also a growing interest in functional and health-focused dog food options.
West Coast Region: The West Coast region, encompassing states such as California, Oregon, and Washington, is known for its health-conscious and environmentally-conscious consumer base. Pet owners in this region often seek natural, organic, and sustainably sourced dog food products. Grain-free, limited ingredient, and holistic formulations are popular among consumers looking to provide their dogs with premium nutrition.
Southwest Region: The Southwest region, including states such as Texas, Arizona, and New Mexico, has a large and diverse pet-owning population. This region sees demand for a wide range of dog food products, including mainstream brands, natural and organic options, and specialized diets. Convenience and affordability are key factors for consumers in this region.
Mountain States: The Mountain states, such as Colorado, Utah, and Montana, have a significant pet ownership rate and a focus on outdoor activities. Dog owners in this region often seek dog food products that support their active and adventurous lifestyles. High-protein, performance-oriented, and grain-free dog food options are popular among this consumer base.
Competitive Landscape – US Dog Food Market
The US Dog Food Market has a highly competitive landscape with numerous players vying for market share. The market is dominated by several key companies, along with numerous smaller and niche players. Here are some prominent players in the US dog food market:
Mars Incorporated: Mars is a global food conglomerate and a major player in the pet food industry. It owns popular dog food brands such as Pedigree, Iams, Nutro, and Royal Canin. Mars' extensive product portfolio and strong brand presence contribute to its significant market share.
Nestlé Purina PetCare: Nestlé Purina PetCare is a subsidiary of Nestlé and one of the largest pet food companies globally. It offers a wide range of dog food brands, including Purina ONE, Purina Pro Plan, and Beneful. Nestlé Purina's extensive distribution network and continuous product innovation contribute to its strong market position.
The J.M. Smucker Company: The J.M. Smucker Company is a leading consumer packaged goods company that entered the pet food market through acquisitions. It owns dog food brands such as Milk-Bone, Meow Mix, and Rachael Ray Nutrish. The company's diverse brand portfolio and market presence contribute to its competitiveness.
Hill's Pet Nutrition (Colgate-Palmolive): Hill's Pet Nutrition is a subsidiary of Colgate-Palmolive and specializes in premium pet food. Its dog food brand, Science Diet, is well-known for its veterinary-recommended formulas. Hill's Pet Nutrition's focus on scientifically formulated pet food gives it a competitive advantage in the market.
Blue Buffalo (General Mills): Blue Buffalo, now owned by General Mills, is known for its natural and holistic dog food offerings. The brand emphasizes high-quality ingredients and avoids the use of artificial additives. Blue Buffalo's positioning in the premium and natural dog food segment gives it a competitive edge.
Champion Petfoods: Champion Petfoods is a Canadian company known for its biologically appropriate dog food brands, such as Orijen and Acana. These brands emphasize high-quality, regional ingredients and a focus on the nutritional needs of dogs. Champion Petfoods has gained popularity among consumers seeking high-protein and grain-free dog food options.
Other notable players in the US Dog Food Market include Merrick Pet Care, Wellness Pet Food, Diamond Pet Foods, Nutro, and Canidae.
The competitive landscape of the US Dog Food Market is characterized by ongoing product innovation, brand loyalty, distribution networks, marketing strategies, and a focus on meeting evolving consumer demands. Companies compete on factors such as product quality, nutritional value, pricing, packaging, and marketing to capture a larger market share in this highly competitive industry.
Which country will dominate the US Dog Food market?
"North East" will lead the US Dog Food market during the forecast period 2023 to 2032.
Which are the driving factors of the US Dog Food market?
The key factors driving the market are Increasing Pet Ownership, Humanization of Pets, Pet Health and Wellness Focus, Premiumization and Innovation, E-commerce and Direct-to-Consumer Channels, Focus on Sustainability and Ethical Sourcing and Veterinary Recommendations and Prescription Diets.
Who are the top players operating in the US Dog Food market?
The key players operating in the US Dog Food market are Mars Incorporated (Pedigree, Royal Canin, Nutro, Iams), Nestlé Purina PetCare (Purina ONE, Purina Pro Plan, Beneful), The J.M. Smucker Company (Nature's Recipe, Milk-Bone, Kibbles 'n Bits), Hill's Pet Nutrition Inc. (Hill's Science Diet, Hill's Prescription Diet), Blue Buffalo Co. Ltd. (Blue Buffalo), Colgate-Palmolive Company (Hill's Science Diet), Diamond Pet Foods (Diamond Naturals, Taste of the Wild), Merrick Pet Care (Merrick), Ainsworth Pet Nutrition (Rachael Ray Nutrish), WellPet LLC (Wellness).
What will be the CAGR of US Dog Food market?
The US Dog Food market is expanding growth with a CAGR of approximately 4.6% during the forecast period (2023 to 2032).
What is the existing size of US Dog Food market?
The US Dog Food market size was valued at USD 44.9 Billion in 2022 and it is projected to reach around USD 55.8 Billion by 2032.
Ayush Kadam is a Senior Market Research Analyst at Custom Market Insights, with over seven years of experience in syndicated and custom market research. He specializes in market sizing, competitive intelligence, industry trends, forecasting, and strategic insights, helping clients turn complex data into actionable business decisions.