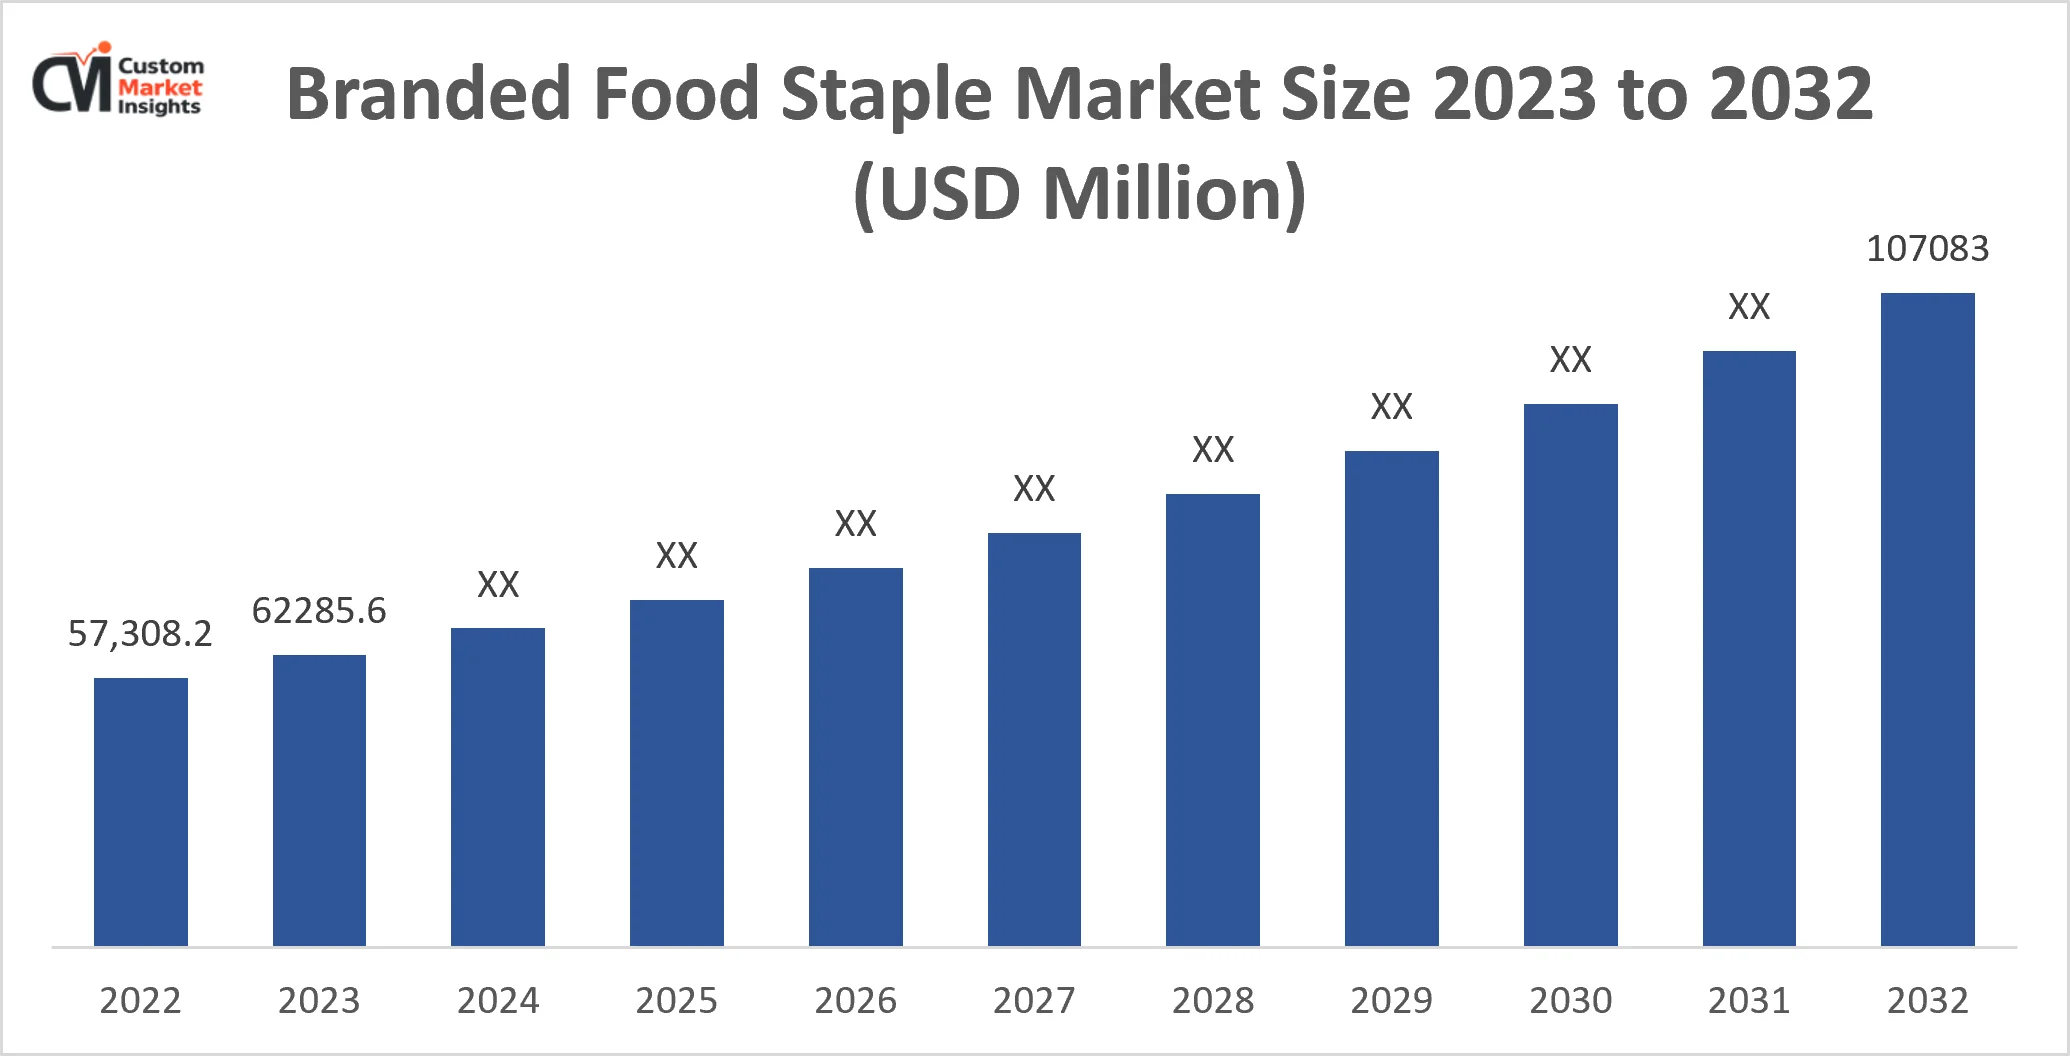
Valued at USD 62.29 Bn in 2023, the market is projected to reach USD 107 Bn by 2032, growing at a 6.6% CAGR. Europe holds the largest share, while Asia-Pacific grows fastest. The report is segmented by product type and distribution channel.
The global branded food staple market was valued at USD 62.29 Bn in 2023 and is projected to reach USD 107 Bn by 2032, growing at a CAGR of 6.6%. Europe is the largest regional market and Asia-Pacific is growing fastest.
Global Branded Food Staple Market 2023–2032 (By Million)
As per the current market research conducted by CMI Team, the global Branded Food Staple Market is expected to record a CAGR of 6.6% from 2023 to 2032. In 2022, the market size is projected to reach a valuation of USD 57,308.2 million. By 2032, the valuation is anticipated to reach USD 107083 million.
Staple Food Insights
Staple Food
Region
Calories per 100g
Protein per 100g
Fat per 100g
Rice
Asia
130
2.7
0.7
Wheat
Europe, Asia
354
13
1.6
Maize
Americas, Africa
337
3.4
1.5
Cassava
Africa, South America
160
1.9
0.3
Potatoes
Europe, Americas
77
2
0.1
Yams
Africa, Asia
112
1.7
0.2
Beans
Worldwide
343
24
1.5
Lentils
Worldwide
295
9
1.2
Peas
Worldwide
240
5.2
0.6
Source: USDA Food Data Central database
The Branded Food Staple Market refers to the segment of the food industry that encompasses branded and packaged essential food items such as rice, wheat, flour, sugar, cooking oil, and other pantry staples. These products are widely recognized, backed by established brands, and cater to consumer demands for convenience, reliability, and quality assurance.
The market for branded food staples is highly competitive, with prominent players vying for market share. It operates on a global scale, serving diverse consumer preferences and dietary needs. The market is characterized by continuous innovation, product diversification, and marketing strategies to meet evolving consumer demands and differentiate brands in a crowded marketplace. Key trends in the branded food staple market include the increasing focus on health and wellness, driving demand for healthier options and clean-label products.
The emphasis on sustainability and ethical sourcing is also prominent, as consumers seek brands that prioritize environmental and social responsibility. Additionally, the market experiences trends such as the rise of e-commerce and online grocery shopping, personalized nutrition, and the growth of plant-based alternatives to cater to changing consumer preferences.
The Branded Food Staple Market presents significant growth opportunities due to several factors:
Changing Consumer Lifestyles and Dietary Preferences: Evolving consumer lifestyles, including increased urbanization and busy schedules, drive the demand for convenient and reliable branded food staples. Changes in dietary preferences, such as the growing popularity of plant-based diets or gluten-free options, also influence market demand.
Brand Recognition and Trust: Established brands in the market benefit from strong brand recognition and consumer trust. Consumers often choose branded food staples over generic options due to the assurance of quality, safety, and consistent standards provided by trusted brands.
Increasing Health and Wellness Awareness: The rising awareness of health and wellness among consumers fuels the demand for branded food staples that align with their dietary goals. Brands offering healthier options, organic or natural ingredients, or products with specific nutritional benefits gain traction in the market.
Technological Advancements in Packaging and Production: Technological advancements in packaging and production processes allow brands to innovate and offer convenience, extended shelf life, and sustainable packaging solutions. Improved packaging technologies contribute to the appeal and functionality of branded food staples, driving market growth.
Sustainability and Ethical Sourcing: There are opportunities for brands to adopt sustainable sourcing practices, reduce environmental impacts, and ensure ethical supply chains. Brands focusing on sustainable farming, fair trade practices, or packaging innovations that minimize waste can attract environmentally conscious consumers and gain a competitive advantage.
Expansion into Emerging Markets: The rising disposable incomes and changing consumer preferences in emerging markets present opportunities for brands to expand their presence. By adapting products to cater to local tastes and preferences, brands can tap into the growing demand for branded food staples in these markets.
Branded Food Staple Market - Mergers and Acquisitions
The Branded Food Staple Market has seen several mergers and acquisitions in recent years, with companies seeking to expand their market presence and leverage synergies to improve their product offerings and profitability. Some notable examples of mergers and acquisitions in the Branded Food Staple Market include:
General Mills and Good Belly: In 2020, General Mills entered a partnership with Good Belly, a probiotic-focused brand. This collaboration allowed General Mills to expand its portfolio into the functional food and beverage category, offering products with added health benefits.
PepsiCo and SodaStream: In 2018, PepsiCo acquired SodaStream, a company known for its home carbonation systems. PepsiCo tap into the growing market for at-home beverages, including flavoured carbonated drinks and sparkling water.
The Kellogg Company's Acquisition of RXBAR: In 2018, The Kellogg Company acquired RXBAR, a manufacturer of protein bars made with simple, clean ingredients. Kellogg's enter the fast-growing protein bar segment and cater to consumer demand for healthier on-the-go snacks.
Mondelez International's Acquisition of Tate's Bake Shop: In 2018, Mondelez International acquired Tate's Bake Shop, known for its premium baked goods. This acquisition expanded Mondelez's presence in the premium cookie and snack category.
These mergers and acquisitions have helped companies expand their product offerings, improve their market presence, and capitalize on growth opportunities in the Branded Food Staple Market. The trend is expected to continue as companies seek to gain a competitive edge in the market.
The Branded Food Staple Market faces several significant threats that could impact its growth and profitability in the future. Some of these threats include:
Price Volatility of Raw Materials: The branded food staple market is vulnerable to price fluctuations of raw materials, such as wheat, sugar, and cooking oil. Fluctuations in commodity prices can impact profit margins for brands, leading to challenges in maintaining price stability and competitiveness in the market.
Intense Competition from Private Labels: Private label products, offered by retailers under their own brand names, pose a significant threat to branded food staples. Private labels often provide similar products at lower prices, enticing cost-conscious consumers and eroding market share for branded products.
Changing Consumer Preferences and Dietary Trends: Rapid shifts in consumer preferences and dietary trends can pose a threat to established brands. Changes in consumer demand for healthier options, organic or gluten-free alternatives, or the rise of new dietary trends may require brands to adapt their product offerings to stay relevant in the market.
Food Safety Concerns: Food safety incidents, such as contamination or product recalls, can severely impact consumer trust and brand reputation. Instances of foodborne illnesses or safety breaches can lead to decreased consumer confidence, reduced sales, and potential legal consequences, posing a significant threat to brands operating in the food staple market.
Report Scope
Feature of the Report
Details
Market Size in 2023
USD 62285.6 Million
Projected Market Size in 2032
USD 107083 Million
Market Size in 2022
USD 57,308.2 Million
CAGR Growth Rate
6.6% CAGR
Base Year
2023
Forecast Period
2024-2033
Key Segment
By Product Type, Distribution Channel and Region
Report Coverage
Revenue Estimation and Forecast, Company Profile, Competitive Landscape, Growth Factors and Recent Trends
Regional Scope
North America, Europe, Asia Pacific, Middle East & Africa, and South & Central America
Buying Options
Request tailored purchasing options to fulfil your requirements for research.
Category-Wise Insights
By Product Type:
Grains and Pulses: Grains refer to cereal crops such as rice, wheat, oats, and barley, while pulses include legumes like lentils, chickpeas, and beans. In the Branded Food Staple Market, grains and pulses are essential food staples. The market trends include a growing demand for organic and specialty grains, as well as the introduction of convenient packaged pulses.
Spices: Spices play a vital role in enhancing the flavours of various dishes. In the Branded Food Staple Market, branded spices are popular for their consistent quality and standardized packaging. The trends include a focus on sustainable sourcing, the introduction of spice blends and seasonings, and the increasing popularity of ethnic and international Flavors.
Value Added: Value-added products in the Branded Food Staple Market refer to processed or packaged versions of staple items. This category includes products like flavoured rice, fortified grains, instant oats, or pre-mixed flours. Trends in value-added products include the introduction of healthier alternatives, innovative packaging formats, and convenient meal solutions.
Others: The "Others" category in the Branded Food Staple Market encompasses various products that are essential food staples but do not fall under the specific categories mentioned above. Include items like cooking oils, sugar, salt, and other pantry staples. The trends in this category include the demand for healthier versions, sustainable sourcing practices, and the use of innovative packaging solutions.
By Distribution Channel
B2B: In the branded food staple market, the B2B (business-to-business) distribution channel involves the sale of branded food staples from manufacturers to businesses, such as restaurants, hotels, and foodservice providers. It encompasses bulk purchasing and distribution for commercial use. The adoption of advanced inventory management systems, and the integration of data analytics to optimize efficiency and meet the evolving demands of B2B customers.
B2C: The B2C (business-to-consumer) distribution channel involves the direct sale of branded food staples from manufacturers or retailers to individual consumers. It includes traditional brick-and-mortar stores, online retailers, supermarkets, and grocery stores. The growing focus on health and wellness, influencing consumer choices towards branded food staples with healthier options and sustainable packaging.
Branded Food Staple Market - Regional Analysis
The Branded Food Staple Market is segmented into various regions, including North America, Europe, Asia-Pacific, and LAMEA. Here is a brief overview of each region:
North America: In North America, a key trend in the branded food staple market is the increasing demand for organic and natural food products. Consumers in this region prioritize health and wellness, driving the growth of brands offering organic and clean-label options. Dominant players in this region include Kraft Heinz Company, General Mills Inc., and The Kellogg Company.
Europe: In Europe, the trend towards sustainable and locally sourced food products is prevalent in the branded food staple market. Consumers in this region value environmental consciousness and prefer brands that prioritize sustainable sourcing practices. Key players dominating the European market include Nestlé, Unilever, and Mars, Incorporated.
Asia-Pacific: The growing middle-class population and increasing disposable incomes are driving the demand for branded food staples. Convenience and ready-to-eat food products are trending, as consumers seek convenient meal solutions in their busy lifestyles. Dominant players in this region include Ting Hsin International Group, Yihai Kerry Group, and Nissin Foods Holdings Co., Ltd.
LAMEA (Latin America, Middle East, and Africa): In the LAMEA region, the branded food staple market is witnessing a trend towards localization and regional flavors. Consumers in this region have a preference for traditional and culturally significant food staples. Key players dominating the LAMEA market include BRF SA, Almarai Co., and Grupo Bimbo.
The Branded Food Staple Market is highly competitive, with a large number of manufacturers and retailers operating globally. Some of the key players in the market include:
Nestlé
Kraft Heinz Company
General Mills Inc.
The Kellogg Company
Unilever
Mars Incorporated
The Coca-Cola Company
PepsiCo Inc.
Mondelez International Inc.
Archer Daniels Midland Company
Others
These companies operate in the market through various strategies such as product innovation, mergers and acquisitions, and partnerships. For example, In 2021, a major partnership in the branded food staple market was the collaboration between Nestlé and Starbucks. This global alliance granted Nestlé the rights to market, sell, and distribute Starbucks-branded packaged coffees and teas, further expanding Nestlé's presence in the premium coffee segment.
Several new players have entered the branded food staple market, adopting innovation and development to establish their presence. These companies focus on introducing unique product offerings, incorporating sustainable sourcing practices, and leveraging technology for distribution and marketing. Examples of new players include start-ups specializing in plant-based alternatives, organic food products, and direct-to-consumer models, aiming to capture niche segments and cater to evolving consumer preferences.
The branded food staple market is dominated by key players with established brands, extensive distribution networks, and a strong market presence. These players have a wide range of product offerings, extensive marketing campaigns, and robust supply chains. They maintain their dominance through brand recognition, trust, and consistent quality. Dominating players often leverage their economies of scale, strong retail partnerships, and investments in research and development to stay ahead of the competition and maintain a significant market share.
Regional Coverage
North America
U.S.
Canada
Mexico
Rest of North America
Europe
Germany
France
U.K.
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
New Zealand
Australia
South Korea
Rest of Asia Pacific
The Middle East & Africa
Saudi Arabia
UAE
Egypt
Kuwait
South Africa
Rest of the Middle East & Africa
Latin America
Brazil
Argentina
Rest of Latin America
CMI.Market Research Report2023-2032
Global Branded Food Staple Market 2024–2033
Updated: September 2026 · Formats: PDF, Excel, PPT
Which are the driving factors of the Branded Food Staple Market?
The key factors driving the Market are Changing Consumer Lifestyles and Dietary Preferences, Brand Recognition and Trust, Increasing Health and Wellness Awareness, Technological Advancements in Packaging and Production, Sustainability and Ethical Sourcing And Expansion into Emerging Markets.
Which type led the Branded Food Staple market?
The "Product Type" category dominated the market in 2022.
Who are the key players in the Branded Food Staple market?
The key players in the market are Nestlé, Kraft Heinz Company, General Mills Inc., The Kellogg Company, Unilever, Mars Incorporated, The Coca-Cola Company, PepsiCo Inc., Mondelez International Inc., Archer Daniels Midland Company, Others.
Which region held the largest market share in the Branded Food Staple market?
"North America" had the largest share in the Branded Food Staple Market.
What is the growth rate of the Branded Food Staple market?
The global market is projected to grow at a CAGR of 6.6% during the forecast period, 2023-2032.
How much is the Branded Food Staple market?
The Branded Food Staple Market size was valued at USD 57,308.2 Million in 2022.
Ayush Kadam is a Senior Market Research Analyst at Custom Market Insights, with over seven years of experience in syndicated and custom market research. He specializes in market sizing, competitive intelligence, industry trends, forecasting, and strategic insights, helping clients turn complex data into actionable business decisions.